Asset Management
Learn what asset management is, the asset classes and skills involved, the roles from analyst to portfolio manager, and how students can prepare.
Introduction
What is asset management?
Asset management, or vermogensbeheer, is the professional oversight of investment portfolios with the aim of growing their value over time. Asset managers set an investment strategy, allocate capital across investments and monitor performance on behalf of individuals, companies, pension funds and governments, always within the client’s goals and risk limits. Because they invest money on behalf of clients, asset management firms are known as buy-side firms.
Asset managers earn most of their revenue from management fees: a fee calculated as a percentage of the assets under management, regardless of whether the portfolio makes a profit that year. Actively managed funds typically charge a higher percentage than passive, index-tracking strategies, because active management requires more research and decision-making. Some funds, particularly hedge funds and certain alternative strategies, also charge a performance fee once returns clear an agreed hurdle. This revenue model is fundamentally different from investment banking, where fees are paid per transaction rather than continuously on assets under management.
Asset classes
What asset managers invest in
Portfolios are built from a mix of asset classes, each with a different role in balancing risk and return.
Within each asset class there is a further choice between active and passive management. Active managers select individual positions in the belief that they can beat the market or a benchmark, while passive strategies simply track an index at low cost. Within equities, a common distinction is between growth and value styles, and within fixed income between duration and credit quality. Multi-asset funds combine several asset classes in one portfolio and shift the weighting between equities, bonds and alternatives as market conditions change.
What they do
What asset managers do
Exactly how this work looks depends on the strategy. Fundamental managers build conviction on a company or sector through in-depth research and conversations with management, while quantitative teams look for patterns in large datasets and translate them into systematic rules. Buy-side research also differs from sell-side equity research: buy-side analysts write for an internal investment team and are judged on the quality of their investment ideas, while sell-side analysts publish research for external clients and are judged on the quality and timeliness of that published research.
Step by step
How an investment decision is made
Most investment teams follow a similar path, from research to a live position that is monitored and adjusted over time. Analysts do much of the research and modelling along the way.
This process does not look the same everywhere. At fundamental, actively managed funds, every step is driven by the judgement of analysts and portfolio managers, often tested by an investment committee before a position is taken. At quantitative and passive strategies, research, selection and allocation are largely automated through models and rules, and the team’s focus sits more on building and validating those models than on individual investment decisions.
Career paths
Common asset management roles
Asset management has a few distinct paths, each with a different balance of research, decision making and quantitative work.
Within each of these paths there is further specialisation. A research analyst or portfolio manager usually focuses on one asset class, such as equities, fixed income or multi-asset, and often on a specific sector or region within it. Quantitative analysts typically work in separate teams that build models for several strategies at once, working closely with both fundamental managers and risk management to test whether a model holds up in practice.
Roles
The asset management ladder
Investment Analyst
The research and data hub for the investment team.
Senior Investment Analyst
Owns a coverage area and shapes recommendations.
Portfolio Manager
Makes the investment decisions and manages the portfolio.
Chief Investment Officer
Sets the firm’s investment direction and process.
Career timeline
How a career progresses
Asset management has a clear ladder. Most people start as an investment analyst, often after experience in equity research, investment banking or another investment role, or straight from an undergraduate or graduate programme. Analysts build the research and models that portfolio managers use to make decisions.
With experience you can move to senior analyst, then to portfolio manager with direct responsibility for investment decisions, and eventually to chief investment officer, who sets the firm’s investment direction. A CFA charter is often seen as a prerequisite to move into portfolio management.
The pace of these steps differs by type of firm. At large, established asset managers each step often takes longer and the path is more formal, with clear job titles and review cycles. At smaller or specialised boutiques the route into portfolio management can move faster, but with less structured guidance. Not everyone follows the full ladder either: many analysts deliberately build a long career as a senior sector specialist without ever becoming a portfolio manager, and that is regarded within the industry as a legitimate career path in its own right.
| Level | Typical experience |
|---|---|
| Investment Analyst | 0 to 3 years |
| Senior Investment Analyst | 3 to 5 years |
| Portfolio Manager | 7 to 10 years |
| Chief Investment Officer | 12+ years |
Compensation
How pay works in asset management
Pay in asset management is competitive and usually made up of a base salary and a performance-related bonus. The bonus tends to grow with seniority and with how much money you are responsible for, so portfolio managers and chief investment officers earn the most. At senior levels, part of the reward can be tied to the performance of the funds you manage.
Concrete figures vary widely by firm, role, location and the type of assets managed, so we do not quote fixed numbers here. A CFA charter, a strong track record and a move into portfolio management are the factors that most influence pay over a career. The hours are more predictable than in investment banking, usually around fifty to seventy a week and shaped by market hours and reporting cycles.
The compensation structure is closely tied to the firm’s revenue model. Because management fees come in relatively steadily as long as assets under management hold up, the base salary is generally secure, while the bonus pool moves with the profitability of the firm as a whole and, for senior investors, with the performance of the fund or mandate they are responsible for. That is why a junior analyst’s bonus is mostly driven by individual contribution and team results, while a portfolio manager’s bonus is more directly linked to measurable investment performance.
A day in the life
A typical day in asset management
The day is built around market hours. Analysts start by reviewing overnight moves, scanning company news and flagging earnings or economic data that affect the names they cover, then bring updated model outputs to the morning meeting. Much of the middle of the day goes into deep research: updating valuation models in Excel, reading earnings transcripts and writing investment memos that propose a clear action.
Portfolio managers lead the morning meeting, work with traders to execute agreed trades and rebalance portfolios, and spend part of the afternoon on client updates and risk reviews. Weeks run to around fifty to seventy hours and get busier during earnings season, market volatility and reporting cycles. It is demanding, but it gives early, direct exposure to markets and to real investment decisions.
This rhythm differs by strategy. At a long-only equity fund, the day revolves mainly around news, results and conversations about individual companies. At a fixed income team, the focus sits more on interest rate developments, central bank policy and credit spreads. Quantitative teams have a calmer rhythm around market news, but spend their time testing and refining models, often working closely with technology and risk specialists.
Analysts
What investment analysts do
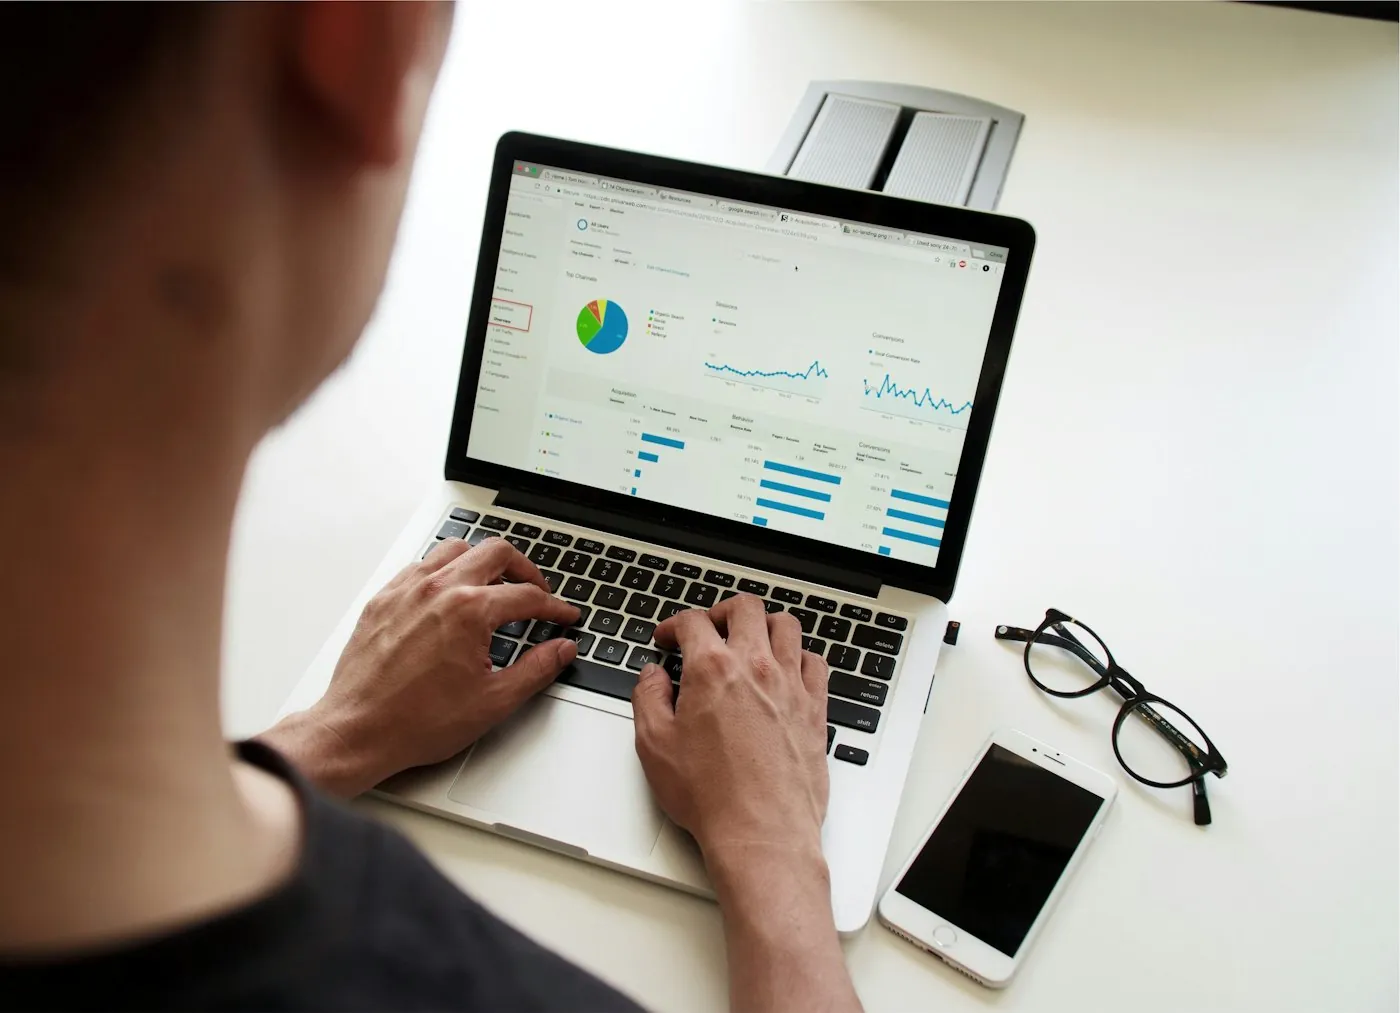
Junior analysts are the research and data foundation the investment team relies on.
This differs from a junior role in investment banking or sell-side equity research. A banking analyst mostly works on deal-driven material for a specific transaction with a hard deadline, and a sell-side analyst writes research that is published broadly. A buy-side analyst in asset management instead builds ongoing coverage of a limited number of names, with the goal of convincing the portfolio manager of a concrete buy or sell idea, not informing an external audience.
- Researching companies, sectors and themes
- Building and updating financial models
- Valuation and scenario analysis
- Preparing investment reports and memos
- Tracking news, earnings and economic data
- Comparing companies and sectors with data
- Stress-testing a thesis against scenarios
- Supporting portfolio and risk reviews
Skills
Skills you need
The skills that matter most differ by role. An analyst mostly needs sharp research and modelling skills, while a portfolio manager relies more on judgement, discipline and the ability to make decisions under uncertainty.
Education
Education and certifications
Most roles start from a bachelor’s degree, with certifications that carry real weight later in a career.
The CFA program consists of three exam levels covering topics such as valuation, portfolio management, economics and ethics, and is largely completed through self-study alongside a job. Many analysts start level one in their final year of study or their first job, so the charter is finished around the time of a move into senior research or portfolio management.
Getting in
How to break into asset management
Most routes in run through research and demonstrable interest in markets, rather than through one fixed career path.
Preparation
How to succeed as a student
What matters most is combining technical skill with genuine, demonstrable interest in markets.
Compare
Asset management versus other paths
The most confusion arises with paths that also involve investing or wealth. These comparisons show where asset management differs from each.
Asset management vs investment banking
Asset management invests money for clients over time. Banking arranges one-off transactions and deals for a fee.
Asset management vs private equity
Asset management mostly invests in listed securities. Private equity buys and owns whole companies.
Asset management vs hedge funds
Traditional asset management is often long-only and benchmark-driven. Hedge funds use broader strategies and can short.
Asset management vs wealth management
Wealth management builds a personalised financial plan and portfolio for one client relationship at a time, often across products from several providers. Asset management runs pooled funds or institutional mandates according to one strategy applied across many investors.
Asset management vs sales and trading
Trading desks buy and sell securities to provide liquidity, execute client orders or take short-term market views, often holding positions for hours or days. Asset management makes longer-horizon investment decisions and typically relies on trading desks to execute the resulting trades.
Asset management vs equity research
Sell-side equity research publishes research and recommendations for a bank or broker’s external clients. Asset management uses its own, internal research to actually invest and manage the portfolio.
Employers
Asset managers active in the Netherlands
A selection of well-known asset managers active in the Netherlands, grouped by type. We only list firms we have verified. Some are global players with a large local office, others are Dutch houses that mainly manage money for domestic pension funds and private clients.
Global asset managers
Asset management at large banks
 Goldman Sachs AM
 J.P. Morgan AM
 Morgan Stanley IM
Dutch asset managers
 Robeco
 Van Lanschot Kempen
 Aegon AM
 Achmea Investment Management
 Triodos IM
Pension asset managers
 APG
 PGGM
 MN
Vacancies
Asset management vacancies
We only show real, current openings with a link to the employer. Internships and analyst roles will appear here. In the meantime, browse all current vacancies.
View all vacanciesResources
Recommended resources
FAQ
Frequently asked questions
What is asset management?
Asset management is the professional oversight of investment portfolios to grow their value over time. Managers set a strategy, allocate capital and monitor performance for clients such as individuals, companies, pension funds and governments, within agreed goals and risk limits.
What is the buy-side?
The buy-side is made up of firms that invest capital on behalf of clients, such as asset managers and pension investors. They buy and hold securities, unlike the sell-side that advises companies and arranges transactions for a fee.
What does an investment analyst do?
Analysts research companies, sectors and markets, build and update financial models, prepare investment reports and track news and earnings. They form the research and data foundation that portfolio managers use to make decisions.
Do you need a CFA for asset management?
Not to start as an analyst, but the CFA charter is highly regarded and is often seen as a prerequisite for moving into portfolio management. Many people begin the program early in their career.
How many hours do asset managers work?
Weeks usually run to around fifty to seventy hours, shaped by market hours and reporting cycles, and get busier during earnings season and market volatility. Hours are generally more predictable than in investment banking.
What skills do I need?
Strong investment research and analytical thinking, financial modelling and valuation, market knowledge, data analysis with tools like Excel, SQL and Python, portfolio construction and risk sense, and clear communication.
What is the difference between asset management and investment banking?
Asset management invests money for clients over time and earns mainly from management and performance fees. Investment banking advises on and arranges one-off transactions, such as deals and capital raises, and earns fees for them.
How do I get into asset management?
Apply for internships and analyst programmes, or move in from equity research or banking. Recruit at target universities, start the CFA, network with people in the field, and build strong research, valuation and communication skills.
Related
Related finance paths
Start your asset management journey
Browse open vacancies or explore the other finance career paths.